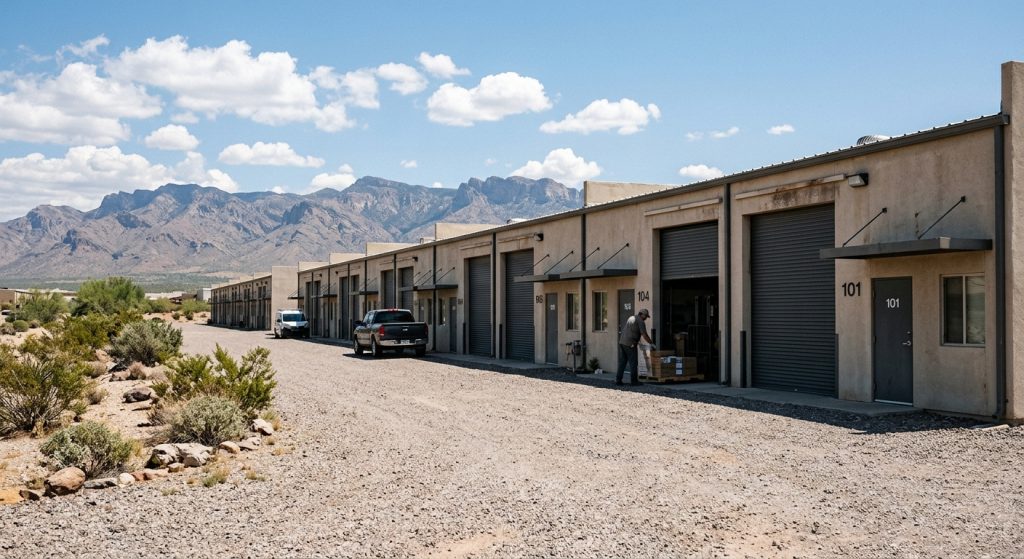
Fourteen multi-tenant business parks in Tucson, Ariz., have traded for $165.75 million in what the brokerage on the deal called the largest industrial sale by price on record in the market.
Equus Capital Partners sold the Tucson Shallow Bay Industrial Portfolio through Pegasus Tucson Owner LLC to Catalyst Real Estate and New York-based Everview Partners. The sale closed Sept. 28 and was announced Oct. 7 by Cushman & Wakefield | PICOR, which represented both sides.
The portfolio holds 85 buildings totaling about 1.25 million square feet, which puts the price near $133 a square foot. At closing it was 90% leased to 452 tenants — an average footprint under 3,000 square feet, and no single occupant large enough to swing the income.
What is in it
The parks sit along Tucson’s established industrial corridors, from Forbes Boulevard and Prince Road on the north side to Speedway Boulevard and East 29th Street. The largest allocations went to Midway Business Park at 4500 E. Speedway Blvd. ($26 million), Dodge Business Center on East 44th Street and South Dodge Boulevard ($18.3 million), Broadbent Industrial Center on North Forbes Boulevard ($17.1 million), Ruthrauff Commerce Center on West Ruthrauff Road ($16.45 million) and Exchange Place at 1870 W. Prince Road ($15.05 million).
The remaining nine — Butterfield Center, Clairemont Plaza, the Coach Drive industrial building, Eastpoint Business Plaza, Midpoint Business Plaza, North Tucson Business Center, Palo Verde Industrial, Town Central Business Park and Commerce Plaza — were allocated between $4.3 million and $11.5 million each.
“Shallow bay” describes exactly this product: small-unit, lower-clear-height space leased to contractors, distributors, service firms and light manufacturers rather than to national logistics tenants. It is the opposite end of the industrial market from the million-square-foot distribution box, and it has drawn institutional capital for the same reason it is hard to build: the rent roll diversifies risk, and the land near the urban core that supports it is largely spoken for.
A five-year hold
Equus assembled the Tucson parks in October 2021, buying them from Reliance Management as part of a roughly $1.15 billion purchase of industrial property in Tucson and Phoenix. The announcement puts the Tucson component of that deal at about $150 million, which makes the current price roughly $15.75 million, or 10.5%, higher after five years of ownership — a modest nominal gain on paper, before any leasing or capital work over the hold.
The announcement also describes the sale as the largest commercial real estate transaction by square footage in the Tucson metropolitan statistical area since 2007. Paul Hooker, a principal at C&W | PICOR, handled the assignment with Cushman & Wakefield’s National Industrial Advisory Group — Will Strong, Michael Matchett, Madeline Warren, Molly Miller and Jack Stamets.
The market underneath
Tucson industrial vacancy was holding at 7.8% in the second quarter of 2026, according to C&W | PICOR’s quarterly report, which credited leasing demand from defense, mining and manufacturing tenants. Defense work in particular has been a Tucson constant, and on our reading it is part of what makes a small-unit rent roll there bankable.
The brokerage’s own record claim is the tell: Southern Arizona has not been where large industrial checks get written. The deal lands in a year when multi-tenant and shallow-bay portfolios have been moving at scale in bigger markets: TPG AG Real Estate and Redfearn Capital paid $628 million for a Southeast industrial portfolio, EQT sold a 46-building, 10.5 million-square-foot Southeast logistics portfolio to LBA Realty, and Speed Bay Warehouse Solutions entered Philadelphia with an $84 million portfolio.
What the Tucson trade adds is a price point. A buyer willing to pay $133 a foot for 85 aging small-bay buildings in a secondary Sun Belt market is pricing the scarcity of infill industrial space, not the growth of e-commerce distribution — and that distinction is increasingly where commercial real estate capital is being allocated.
The announcement does not disclose financing terms or the buyers’ plans for the portfolio.