Mortgage rates reached a three-year high this week, the Federal Reserve’s own record showed most of its officials still expect another increase before the year is out, and the Fed published a number that captures the strange position American homeowners are in: more equity than ever, accumulating more slowly than before.
Taken together, the week sharpened a divide that has defined 2026. Households that already own are sitting on historically large balances. Households trying to buy are facing the most expensive financing since 2023.
Rates: a seventh straight rise, then a pause
Freddie Mac’s Primary Mortgage Market Survey put the 30-year fixed-rate mortgage at 7.40% on Oct. 8, up from 7.28% the week before and the seventh consecutive weekly increase. A year earlier the same survey read 6.30%. The 15-year fixed averaged 6.73%, up from 6.60%.
The move was smaller than the previous week’s, when the 30-year posted its biggest one-week jump since 2022. And the bond market that drives mortgage pricing actually steadied as the week went on. Treasury Department data shows the 10-year yield at 5.31% on Monday, 5.22% on Thursday and 5.24% on Friday — easing, but above 5% every day of the week. That is the level that matters: 30-year mortgage pricing tracks the long end of the curve, and nothing in this week’s data moved it decisively.
The Fed hardened its signal
The minutes of the September FOMC meeting, released Oct. 7, showed that most participants expected another rate increase by year end. That is the clarifying development of the week. Through late September, the market could read softer labor data as a reason the Fed might stop. The minutes removed that comfort, and they are the committee’s own account rather than a speech by one official.
For anyone advising buyers, the practical consequence is that the case for waiting out a near-term rate decline got weaker this week, not stronger.
A record built on the past, not the present
The Fed’s Survey of Consumer Finances, out Oct. 9, reported that median home equity reached a record $230,000 in 2025 while its growth slowed sharply. Both halves of that sentence matter. The level reflects years of price appreciation that already happened. The deceleration reflects a market where prices have stopped doing the work.
That is the backdrop against which lenders are competing for a shrinking pool of transactions, and it explains a good deal of the industry news below.
Policy and risk
The Department of Housing and Urban Development proposed a significant change to manufactured-housing rules, moving to drop the permanent-chassis requirement and extend its construction code to buildings of five units or more. If adopted, it would let factory-built construction compete for infill and small multifamily sites it has effectively been shut out of. This is a proposal, not a rule, and the comment process will determine what survives.
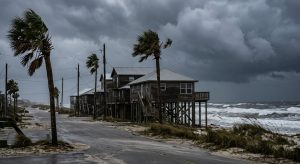
On the risk side, Hurricane Isaias put Florida’s reformed insurance market under live conditions. Citizens Property Insurance suspended binding statewide as the storm approached. As of the National Hurricane Center’s 1 p.m. CDT advisory on Oct. 9, Isaias carried maximum sustained winds of 120 mph and was moving north at 17 mph toward the northern Gulf Coast, with the center warning of “conditions rapidly deteriorating” there. Claims experience, not pre-storm underwriting decisions, will show whether the reforms changed anything.
The industry consolidated, again
Four deals or moves in five days pointed the same direction — platforms buying their way closer to the mortgage.
eXp Realty formed a mortgage joint venture with Newrez and opened its transaction data to agents’ own AI tools. PLACE bought Ardley, a loan-retention software company, two weeks after buying Maxwell. Equifax reported that VantageScore 4.0 mortgage pulls rose 230% from April to August and said it will hold that score’s price at $1 through the end of 2028. And in commercial, a privately held investor offered $2 billion in cash for every hotel owned by Service Properties Trust — an unsolicited bid for a REIT trading well below the value TKO puts on its lodging assets.
The common thread is margin. When transaction volume will not grow, firms buy the adjacent revenue, or buy the assets of companies the market has marked down. Both were on display this week.