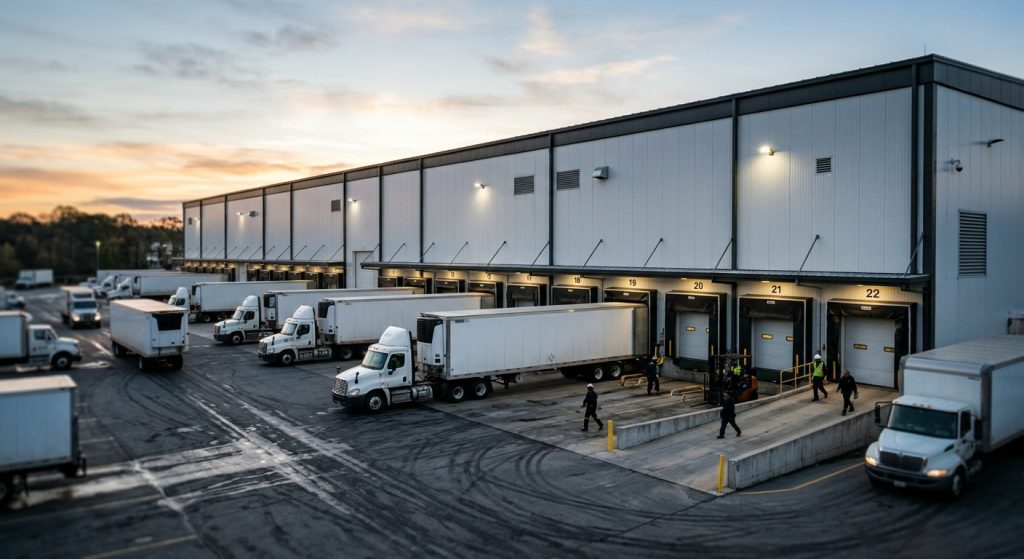
Lineage, Inc., the cold-storage warehouse owner that calls itself the world’s largest temperature-controlled warehouse REIT, lowered its 2026 earnings outlook on Nov. 9 after a third quarter in which its warehouse occupancy improved but costs and a weaker logistics business squeezed profit. The Novi, Mich.-based company now expects full-year adjusted EBITDA of $1.25 billion to $1.27 billion, down from the $1.26 billion to $1.29 billion range it gave in August.
Total revenue for the quarter ended Sept. 30 slipped 1.2% from a year earlier to $1.361 billion, according to the company’s third-quarter earnings release, filed with the Securities and Exchange Commission. Lineage reported a GAAP net loss of $173 million, or $0.68 per diluted share, compared with a $112 million loss in the third quarter of 2025. Adjusted EBITDA fell 7% to $317 million, and adjusted funds from operations (AFFO), the cash-flow measure REITs use to gauge dividend capacity, fell 14.9% to $188 million, or $0.73 a share.
What Lineage says went wrong
Chief Executive Greg Lehmkuhl described the quarter as two different stories. “Our core business trends continued to stabilize in the third quarter, with same-store occupancy growing year-over-year for the second consecutive quarter, further confirmation that customer inventory levels have normalized,” he said in the release. But he added that the company “saw a more challenging environment later in the quarter, as sharply higher oil prices, constrained trucking capacity, and tariff uncertainty created temporary headwinds, particularly in our Global Integrated Solutions business.”
“We expect these pressures to continue into the fourth quarter and have adjusted our guidance accordingly, but we view them as cyclical rather than a change in our trajectory,” Lehmkuhl said.
The segment figures bear out where the pain landed. Global Integrated Solutions, the segment that houses Lineage’s services beyond warehousing, including transportation, posted revenue of $352 million, down 3.3%, while its net operating income fell 13.8% to $56 million and its margin narrowed by 2 percentage points to 15.9%. Fuel costs have been rising elsewhere in the real estate economy as well; RealtyWire has reported that construction input prices had jumped nearly 12% in a year as diesel more than doubled.
Warehouses fuller, but less profitable
In the 419 warehouses Lineage has operated throughout both periods, physical occupancy rose to 76.2% from 75.1%, and economic occupancy, which counts pallets customers have contracted to pay for, edged up to 82.5% from 82.2%. Same-warehouse revenue rose 0.4% to $917 million.
Pricing and costs moved the other way. Storage revenue per physical occupied pallet in those same warehouses fell 2.2% to $67.90, and throughput pallets, a measure of how much product moves in and out, declined 1.1%. Power costs climbed 12.7% to $62 million and labor 2.1% to $346 million. The result was same-warehouse net operating income of $342 million, down 4.2%, with the margin falling to 37.3% from 39.1%.
Across the full Global Warehousing segment of 478 sites, revenue was essentially flat at $1.009 billion, down 0.4%, while segment NOI fell 6% to $361 million.
Below the operating line
Two items widened the GAAP loss beyond the operating trends. Net interest expense rose to $92 million from $68 million a year earlier, and long-term debt stood at $6.81 billion at Sept. 30, up from $6.11 billion at the end of 2025. And the income statement carried $109 million of restructuring, impairment and losses on disposals, against a $5 million gain in the prior-year quarter; the company’s reconciliation tables separately list a $105 million loss on property destruction, which Lineage excludes from its adjusted EBITDA and AFFO. The earnings release does not describe the underlying event.
A narrower range, not a lower midpoint, for AFFO
The guidance change is less severe on a per-share cash-flow basis than on EBITDA. Lineage now expects 2026 AFFO of $2.86 to $2.98 a share, a tighter band than the $2.80 to $3.05 it projected in its second-quarter release on Aug. 5. On our arithmetic the midpoint of that range is unchanged at about $2.92, while the EBITDA midpoint falls by $15 million, to $1.26 billion. The guidance excludes unannounced acquisitions, divestitures and developments.
The board declared a quarterly dividend of $0.5325 a share, an annualized $2.13, which remains below the low end of the company’s full-year AFFO forecast.
Lineage operated 497 facilities with about 87 million square feet and roughly 3.1 billion cubic feet of capacity across North America, Europe and Asia-Pacific as of Sept. 30, serving food and beverage producers, retailers and distributors. That scale makes its results a read on the food supply chain’s appetite for refrigerated space, a niche of the commercial real estate market distinct from the broader warehouse sector. Other parts of the storage world have been consolidating this year, including Public Storage’s $10.5 billion purchase of National Storage Affiliates.
On our reading, the quarter supports management’s view that customer inventories have normalized: occupancy is rising again. What it does not yet show is pricing power, with revenue per pallet down and power costs climbing faster than revenue. Management discussed the results on a conference call at 8 a.m. Eastern on Nov. 10.